


The Study In Brief
Multi-employer, contingent-benefit pension plans cover hundreds of thousands of current and former employees of Canadian governments, and millions more in Canada’s broader public sector – employers such as hospitals, school boards, and colleges. Understanding the value of these plans’ obligations, and whether their financial condition affects governments’ ability to deliver services without tax hikes, is important. The ways governments report the annual operations, and cumulative assets and liabilities, of broader-public-sector pension plans need re-examining.
Reporting of pension costs as they accrue, and net obligations at a point in time, is tricky. Pension payments will occur in the future – projecting even the simplest payment requires choosing a discount rate – and are subject to uncertainties such as longevity and future salaries. Many major pension plans in the broader public sector have benefits that are contingent on their funded status. Moreover, many major plans are multiemployer plans – even when governments are the unique or majority funders of the employers, it is not clear that governments are, or should be, responsible for funding shortfalls if a plan gets into trouble.
The Public Sector Accounting Board is reviewing accounting standards that could affect the entities consolidated in government financial statements and the ways they report contingent pension plans. This paper makes several recommendations to foster more complete and informative reporting related to multiemployer, contingent-benefit plans in Canada’s broader public sector.
A key one concerns public-sector employers whose pension plans create exposure beyond the contributions they make each year, but show their annual contributions as their only cost, and no pension-related obligations on their balance sheets. We need clearer criteria for identifying contingent pension plans – often referred to as target-benefit plans – that involve employer-side funding risk that is genuinely small enough to ignore. The sponsors and managers of those plans, and their participants, likely also need more clarity about who bears the risks in, and how to govern, a plan that guarantees stable contributions to employers.
When employer-side risk is material, users of financial statements should see it. The best place to report it is in the financial statements of the employer. Some provincial governments currently show costs and obligations of pension plans in their broader public sectors that do not appear in the financial statements of the employers themselves. A province might choose to increase its support for employer organizations when their employee pension plans are in trouble. But showing these costs and obligations at the provincial level suggests a more active provincial role in the plans and the employers than is appropriate. Worse, if it leads employers and plan participants to expect a bailout, it creates a moral hazard – making a bailout likelier to be needed.
Canada’s multi-employer contingent-benefit plans are large and growing. Transparency about their costs and who bears the risks in these plans needs to keep pace.
Introduction
Government financial statements help Canadians understand how their governments have provided and funded services in the past, and what their capacity to deliver those services will likely be in the future.
Meaningful and transparently presented statements of operations show governments’ expenses, i.e., the resources they commit to provide services and make transfer payments. They also show governments’ revenues, i.e., the resources they appropriate through taxes and fees. Meaningful and transparently presented statements of financial position inform judgements about governments’ capacity to deliver services while making manageable claims on resources in the future.
From their inception in the 1980s, Canadian public sector accounting standards (PSAS) have reached a high level of coherence and consistent application. As a series of C.D. Howe Institute studies has documented, Canada’s senior governments – the federal government, the provinces and the territories – generally adhere to PSAS in the audited financial statements they release after the end of each fiscal year, and most of them follow the same conventions in the budgets they present around the beginning of each year. At the municipal level, adherence to PSAS in financial statements is good, and more municipalities are presenting PSAS-consistent numbers in their budgets as well.11 Robson and Omran (2019a) provides our latest report card on the quality of financial presentations by Canada’s senior governments. Meanwhile, Robson and Omran (2019b) provides our latest report card on the quality of financial presentations by Canada’s major municipal governments.
As in the private and not-for-profit sectors, ideas about how to present meaningful and accessible information in governments’ financial statements continue to evolve. One particularly challenging area is accounting for public-sector pensions. Modern governments, and the organizations they control and fund, are labour intensive. Their employees receive significant compensation, not when they deliver their services, but later – notably after they retire. Representing the value of future payments that may or may not occur in full is inherently difficult.
The organizations that are largely under government control and largely depend on government funding are heterogeneous - major categories being school boards, hospitals, and post-secondary institutions. The types of pensions they provide are heterogeneous as well. The multi-employer plans that are the focus of this survey differ in their provisions and governance. This heterogeneity complicates decisions about whether and how to report pension obligations. Moreover, because financial statements should present information to inform decision-making, the manner in which pension costs are reported, along with the assets and liabilities of pension plans to which an entity may have exposure, may affect decisions. Gaps and inconsistencies may produce problematic decisions – by governments themselves and/or by employers and others involved in pension arrangements.
Canada’s PSAS arbiter, the Public Sector Accounting Board (PSAB), is currently reviewing its standards for public-sector financial reporting. Two major questions at issue are accounting for deferred compensation – mainly pensions – and defining the reporting entity. This Commentary examines these questions, surveys current pensionrelated reporting in the financial statements of employer organizations and provincial governments, and makes some recommendations.
With respect to the choice of what pensionrelated operations and obligations to report, this review highlights a potential gap. Some publicsector organizations participate in multi-employer, jointly sponsored plans22 Jointly sponsored plans include representatives of employers and participants in their governance. that create exposure for employers beyond the contributions they make each year. Yet the financial statements of these organizations do not report this exposure: their operational statements show only the employer contributions made during the year. This approach makes sense for defined-contribution plans, which create no exposure beyond those annual contributions and could make sense for targetbenefit plans that create employer-side exposure so small that it is safe to ignore. It does not, however, make sense for plans that create material exposure.
Canadians need clearer criteria for identifying pension plans whose employer-side funding risks are small enough to ignore. As well, the plans’ sponsors and managers need more clarity about governance and fiduciary practices that fulfil that requirement. For their part, participants in those plans likely need better understanding about the risks they bear, including the relative risks born by members who are still working and contributing and those who are retired.
In cases where employer-side risk is material, we need more consistent disclosure. Showing only contributions may have been justifiable in the past when the information needed to reflect this exposure was hard to access and use, but advances in information technology and rising standards are changing the cost/benefit analysis in favour of greater analysis and disclosure. Adding notes to financial statements is a potential interim measure, but when an employer has exposure to funding risk, the pension plan and the employer should identify and report it where taxpayers can see and understand it.
With respect to reflecting multi-employer pension plans in provincial financial statements, this review highlights a potential problem. More complete reporting in employers’ financial statements will automatically produce more complete reporting in provincial financial statements in the case of consolidated employers. However, when this is not the case – i.e., when the employers use defined-contribution accounting or when the employers are not consolidated – the widespread practice of reflecting pension-related exposure in provincial financial statements needs rethinking.
Including an employer or pension plan in a government’s financial statements is not only a judgment about current control and financial exposure, it may affect future control and exposure. To the extent a government’s financial statements do include the revenues, expenses and financial position of an organization, that government will take a more active interest in the revenues, expenses and financial position of that organization.
Relatedly, inclusion may imply a government backstop. If the employer or plan managers and participants infer a possible backstop, the backstop might, as a result, become more necessary – a vicious circle. Therefore, appropriate reporting of pension exposure in employers’ financial statements and provincial reporting of consolidated employers’ exposure would be a better approach.
Why Good Reporting of Deferred Compensation Matters
Notwithstanding the measurement challenges just mentioned, a handful of available statistics confirm that public-sector pensions are big enough to matter to governments’ fiscal positions and the Canadian economy. Modern governments employ large numbers of people at considerable cost. Statistics Canada’s Labour Force Survey showed that about one-quarter of employed Canadians (3.9 million out of a total of 16.2 million) worked in the public sector at the end of 2019.33 See Statistics Canada, Labour Force Survey, Table: 14-10-0288-01, which classifies as public-sector employees those employees who work for a local, provincial or federal government, for a government service or agency, a Crown corporation or for a government-funded establishment such as a school (including universities) or hospital. The mix of current versus deferred compensation in the public sector tilts toward deferred more than in the private sector, making public-sector pensions more important than the jobs numbers alone would suggest.44 Robson (2017) shows annual benefit accrual in a public-sector-style pension plan to be between twice and three times the contribution limits for defined-contribution plans or RRSPs. These numbers escape notice partly because public-sector plans use unreasonably high discount rates to value future benefits (Robson and Laurin 2018). Statistics Canada’s pension satellite accounts show that twothirds ($66 billion out of a total of $101 billion) of disbursements from pension plans in 2018 were from public-sector plans and that public-sector plans held more than two-thirds ($1.5 trillion out of a total of $2.2 trillion) of the assets in employerbased plans.55 Trusteed plans plus consolidated revenue fund arrangements. See Statistics Canada, Pension Satellite Account, Tables 3610-0577-01 and 36-10-0576-01.
Substantial deferred compensation will affect governments’ future capacity to deliver services. Public-sector employment grew quickly when baby boomers were entering young adulthood from the mid-1960s through the 1980s. As that generation retires, its pension promises turn into cash payouts. Current yields on highly rated securities – of a quality the average pension-plan participant would think appropriate to back her or his pension promise – have recently been very low. Meanwhile, the COVID-19 crisis has led to fresh demands on government programs and further lowering yields on highly rated securities. It matters greatly whether these plans hold sufficient assets to cover their promised benefits and whether they are collecting sufficient contributions to cover benefits accruing in the present. To make informed judgments about that, taxpayers and elected representatives need financial statements that provide reliable information about governments’ pension-related costs and obligations.66 Governments have many other liabilities that are contingent or hard to put values on – environmental remediations being a major example. The fact that other liabilities may not appear in governments’ statements of financial position, or may not appear in full, does not justify omitting pensions. Pensions are quantifiable in ways that environmental remediations, for example, are not, because the value of accruing benefits to the employee is quantifiable in a way that an environmental obligation is not.
Suppose a plan to which a government has direct or indirect risk exposure has assets that exceed its obligations. Over time, the plan’s surplus will reduce the governments’ need to contribute to the plan or financially support employer organizations that fund it. If the surplus plan does not appear in the government’s financial statements, the government then has more capacity to deliver services than its financial statements indicate. As a result, other programs could be richer, taxes could be lower or the plan participants could receive greater compensation.
By contrast, suppose a government has exposure to a plan with obligations that exceed its assets. Over time, the plan’s deficit will increase the government’s need to fund the plan or increase support to the organizations that fund it. If one excludes these obligations from the government’s financial statements, the statements will overstate the government’s capacity to deliver services. The government may have to borrow to fund its pensions. It may have to raise taxes or squeeze other programs, including employee compensation.
Alternatively, a government might include a pension plan in its financial statements but not have the indicated exposure – no actual claim on a surplus or obligation to cover a deficit. A healthy plan would make the government’s service capacity look bigger than it should. An unhealthy one would make it look smaller than it should.
The implications of reflecting or not reflecting pension-related costs and obligations in a government’s financial statements go beyond judgments about the government’s capacity to deliver services. Accurate measures of total publicsector compensation are also helpful for reasons of efficiency and fairness. Historically, decisions about current and deferred compensation have tended to occur at different times and different settings, without reference to the appropriateness of the resulting total. The bottom line matters for governments, especially when – as will be true for most Canadian governments in the years ahead – their accumulated deficits are a concern.
Entities that affect governments’ budgets, yearend results and balance sheets attract more political attention than entities that do not: governments will likely face pressure to operate or present results in ways that reflect their priorities.77 Usher (2020) discusses how Alberta’s consolidation of universities affects incentives to obtain non-government funding. The University of Victoria’s 2018 financial statements note that BC requires it to present information that prompts a qualified opinion from the provincial auditor general. See www.uvic.ca/vpfo/accounting/assets/docs/financial/ uvicfinancialstatements/financial-statements-2017-18.pdf. Moreover, reflecting a pension plan in a government’s financial statements might make the plan’s participants and managers think the government likelier to backstop it in the event of trouble. That expectation might foster laxer scrutiny or poorer management, which in turn might make the backstop likelier to be called upon.
In summary, a greater focus on how governments and public-sector employers report their pension obligations is important and timely. The evolution of PSAS and the ways governments respond to PSAS changes will matter.
Two Key Questions
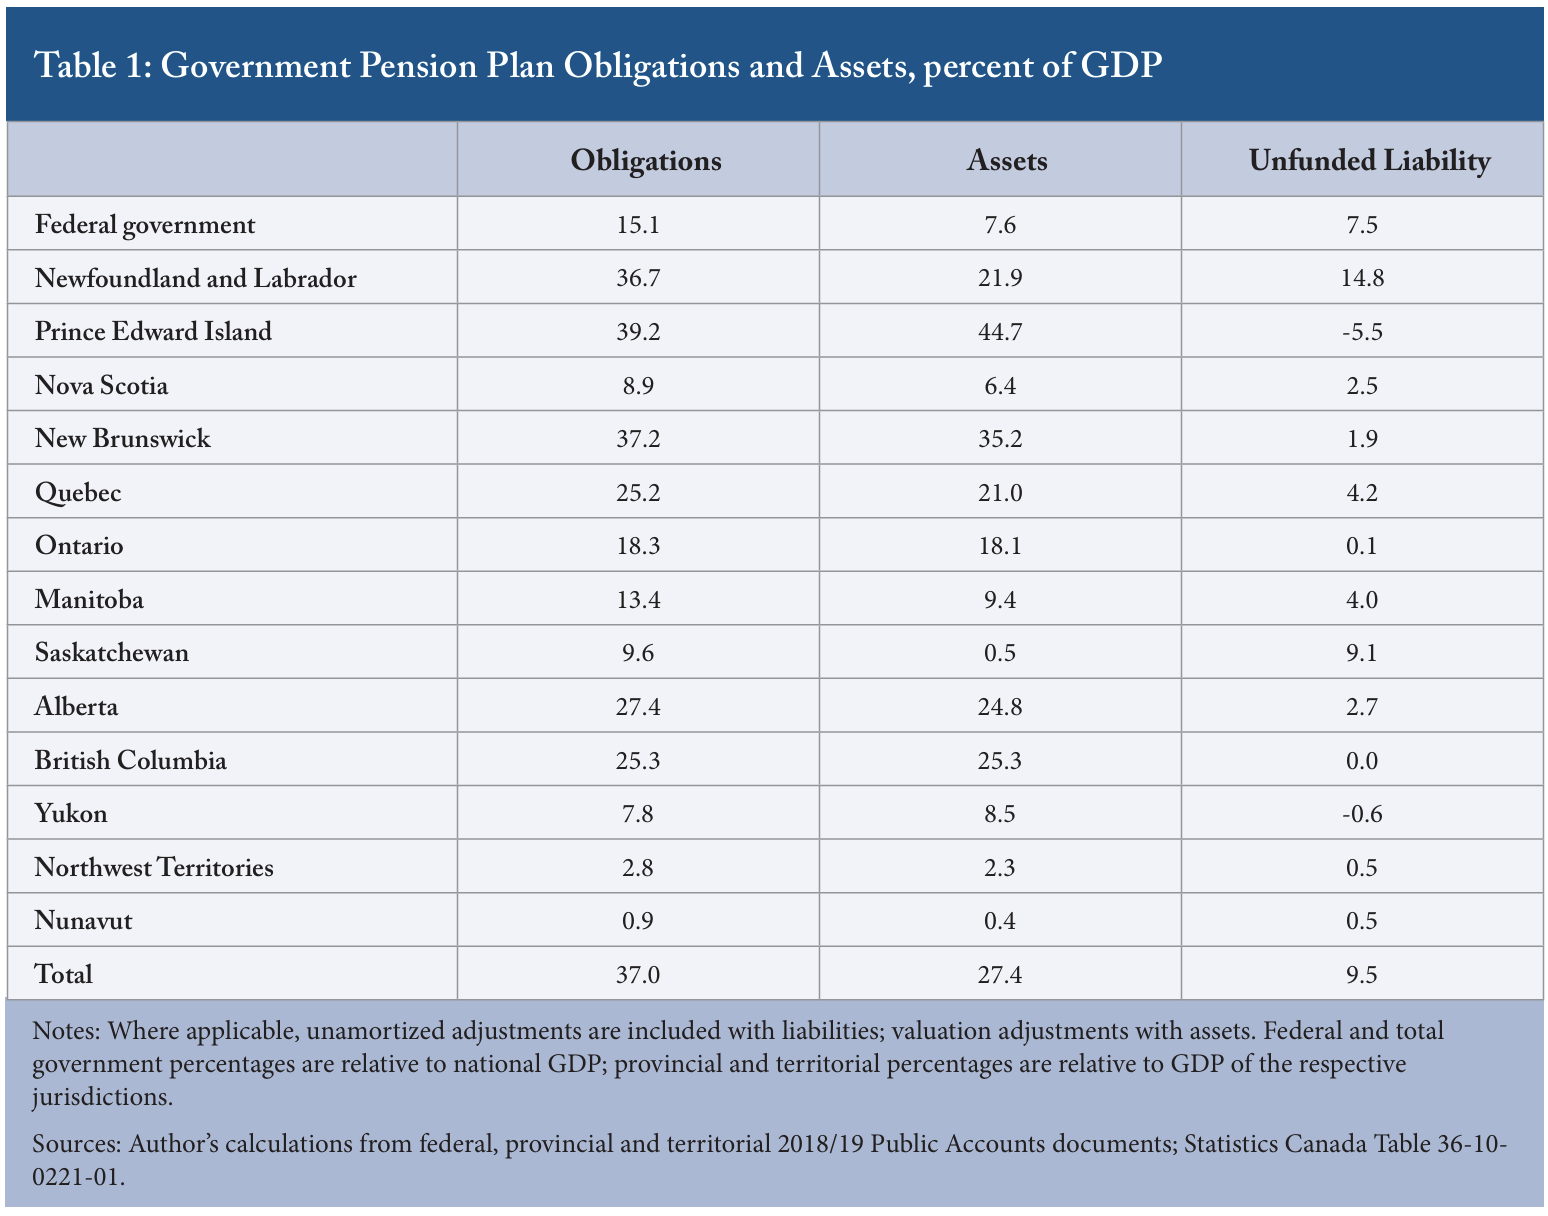
Canadian governments’ financial statements contain numbers that capture aspects of the operations, assets and liabilities of many public-sector employee pension plans. Table 1 reproduces some of the salient numbers from the federal, provincial and territorial governments’ most recent financial statements.
The numbers confirm that the stakes in measuring and presenting government employee pension plans are high. But they are less definitive than this presentation makes them look. Decisions about what and how to report are not straightforward.
It is hard to put a value on a dollar that will be paid in the future, and harder to put a value on a dollar that may or may not be paid in the future. Underestimate the value of promised future pension benefits, and the cost of total current compensation will appear lower than it actually is, and the plan will not accumulate sufficient assets to cover future payouts. Overestimate them, and the cost of current compensation for government employees will appear higher than it actually is, and the plan will accumulate more assets than needed.
Determining the appropriate reporting entity is also a challenge. Ideally, a government’s financial statements would include the operations and financial positions of entities it controls and to which it has material financial exposure. Control and exposure, and the relationship between them, are not always clear cut. But the task is critical. Too narrow a definition will exclude important activities, assets and liabilities from scrutiny. Too broad a definition will increase the expectations and temptations for legislators and officials to act in areas where they should not.
Yes or No? Obligations Beyond Current Contributions
An appropriate starting place is the question of whether an employer should show any pensionrelated obligations at all.
Defined-Contribution Plans:
Pension Expense equals Contributions In defined-contribution (DC) pension plans, current compensation of employees is straightforward – a dollar is a dollar. From the employer’s point of view, DC pension plans are like current compensation because an employer’s annual contribution fulfils its funding obligation for that year. DC pension assets always equal liabilities: participants’ retirement incomes will come entirely from contributions and investment income accumulated in their accounts. With DC plans, there are no pension-related gains and losses, or outstanding assets and obligations, for an employer to report.
Defined-Benefit Plans: Annual and Accrued Obligations
Defined-benefit (DB) pension plans promise future payments based on formulas linked to length of service and salary, and potentially other characteristics such as spousal status at retirement and variables such as inflation. Sponsors of such plans, which may include employers, employees or both, are effectively insurers with obligations to fund payouts with a present value that will typically not equal the market value of the plans’ assets at any point in time. Annual accruals of benefits will typically be different from contributions. So DB plans have balance sheets: cumulative surpluses and deficits.
DB plan sponsors can usually reduce contributions if the plan has a surplus. And they must increase contributions if the plan lacks sufficient assets to cover its obligations. The federal government plans captured in Table 1, and many plans that cover provincial and territorial government workers, are DB plans with a sole sponsor: the government.88 Public service workers in the territories participate in the federal government’s public service plan. They should be, and are, consolidated in the financial statements of those governments.99 A defined-benefit pension plan that requires employee contributions, as the federal government’s plans do, may respond to a surplus by lowering employee contributions, or respond to a deficit by raising them. In single-employer plans, however, it is reasonable to assume that changes in employee contributions will affect gross compensation fairly directly, so reflecting all of the plan’s surplus or deficit in the sponsor’s financial statements makes sense.
But what determines the reported annual cost of accruing benefits in a DB plan and the sum of those benefits over time; i.e., the liability in its statement of financial position? Future payments depend on variables whose future values are unknown. Legal definitions may not capture economic realities.1010 For example, an employer with an obligation to provide a pension that is a fixed percentage of salary may reduce salaries below what they would otherwise have been to indirectly reduce a pension that is impossible to reduce directly. New information will require revisions to past quantifications. Reflecting those revisions in annual statements of operations and financial position is not easy. Furthermore, doing it in a way that is understandable to non-expert readers of financial statements is very hard.
In the past, two practices played a key role in the estimation of pension plans’ current operations and cumulative positions: discounting using assumed rates of return, and delaying or smoothing recognition of changes.
In discounting, pension sponsors and others calculated the present value of future payments using discount rates based on the returns they assumed invested assets would earn over the relevant period. This approach was widespread standard practice, making it appear acceptable even in plans that did not hold assets that could earn the assumed returns.
When the passage of time produced asset values different from those in the plans’ return assumptions, or revealed that other variables such as earnings or longevity needed updating, accountants smoothed the revisions’ impact on the plan’s financial position. Plans would typically recognize changes in asset values larger than a specified size corridor over a period of years, and amortize changes in benefit obligations – including changes resulting from applying a different discount rate – over the average expected time to retirement of the relevant participants.
This flexibility in discount rates and timing of recognition produces financial statements that are impenetrable to non-experts.1111 A stark example of a pension accounting term arising from deferred recognition that is utterly opaque to non-experts is “unamortized actuarial gain” as a liability on the balance sheet and “unamortized actuarial loss” as an asset. Proponents of these approaches too rarely acknowledge the barrier they create to a layperson’s understanding, and it is reasonable to suspect that the barrier might be attractive to someone seeking to obscure the cost or shaky finances of a pension arrangement. Not coincidentally, it creates opportunities to exaggerate the financial health of DB plans. In the private sector, failures of underfunded plans sponsored by employers who became insolvent just when their guarantees were needed have made accountants and regulators less sympathetic to these approaches. However, they are still common in the public sector.1212 Robson and Laurin (2018) show that valuing Ottawa’s pension obligations at a discount rate based on other federal debt reveals the unfunded liabilities in its pension plans, including that for the Canadian Forces, to be much larger than its financial statements report. The federal government’s 2019 economic and fiscal update (Finance 2019) reflected accounting changes related to pensions and other deferred compensation that added several billion dollars to the federal deficit. The PSAB is considering changes to those approaches, which may affect the presentation of information related to pension plans that governments include in their financial statements.1313 PSAB (2016) discusses potential changes to timing of recognition and PSAB (2017b) discusses potential changes to discount rates.
Contingent Plans: Uncertain Employer Exposure
Concerns about the inflexibility, sustainability and taxpayer exposure in traditional DB plans inspired the crafting of a hybrid intermediate pension model with benefits linked not only to the variables referenced by DB plans, but also to the plan’s financial position – the degree to which its assets cover its obligations. Making benefits contingent on the financial health of the plan means that unexpected developments in longevity, investment returns and other factors will not affect just the participants’ benefits, as they would in a DC plan, or just the contributions of sponsors, as they would in a DB plan, but both. A useful term for these hybrid plans is contingent pension plans (Gros and Sanders 2019).
To emphasize, such contingent plans are not like DC plans, for which employers record their contributions to the plan as expenses, with no separate tracking of the annual or accumulated value of accruing benefits. The value of accruing benefits for which the employer is responsible each year in a contingent plan, being calculated in part with reference to variables such as participants’ earnings and employment history, might by coincidence exactly equal the employer’s contributions in a given year, but it will typically be different. Likewise, the cumulative value of accrued benefits in a contingent plan might by coincidence equal its assets at a point in time, but it will also typically be different.
The Ontario Teachers Pension Plan is an early and much-noted example of a contingent plan, in which future benefit accruals – though not past accruals – depend on the plan’s funded status. More recently established examples include the Nova Scotia Teachers Pension Plan and the Nova Scotia Health Employees Pension Plan. Their flexibility in the event of stress has made them widespread in Canada’s public sector since the 1990s – at the time of writing, the Ontario Municipal Employees Retirement System (OMERS), currently a pure defined-benefit plan, has decided to make future inflation-indexation accruals contingent on the plan’s funded status.
By now, many major pension plans with extensive public-sector participation are not in the polar cases of either DC plans, which do not require separate reporting of their activities, or DB plans, which do. As a result, questions about how to reflect contingent plans in the financial statements of participating employers and governments are becoming more pressing. The challenge of representing the financial operations and positions of contingent plans is also on the PSAB’s agenda (PSAB 2017a).
Target Pension Arrangements: Employer Exposure Too Small to Matter?
Some contingent plans have so much benefit flexibility that participants have essentially all the exposure to down- or up-side developments. Frequently referred to as “target benefit” plans, these plans allow reduction, not just of future benefit accruals, but past ones as well, if things go badly.1414 See Gros and Sanders (2019) and Steele et al. (2014). A recent amendment to Canada’s actuarial standards related to commuted values in pension plans singles out the option to reduce accrued benefits as the defining feature for such a “Target Pension Arrangement.”1515 “[A] target pension arrangement is a pension plan for which applicable legislation contemplates the reduction to the accrued pensions of plan members and beneficiaries while the pension plan is ongoing as one of the available options for maintaining the funded status of the pension plan, and where the reduction in accrued pensions is not necessarily caused by the financial distress of the plan sponsor or sponsors.” (Actuarial Standards Board, 2020, p. 3042) The cover memo to the new standards notes that the definition of TPAs would not extend to Jointly Sponsored Pension Plans, largely because accrued benefits in these plans cannot be reduced while the plan is ongoing. (https://www.cia-ica.ca/docs/defaultsource/2020/220008e.pdf.) Such plans reduce funding risk for employers, potentially to the point where it is safe to ignore.
Many governments and public-sector employers omit pension-related information from their financial statements on the grounds that their exposure is too small to matter. In Nova Scotia, for example, the government records only its annual contributions to the main plan for public servants as expenses, as it would in a DC plan.1616 See https://notices.novascotia.ca/files/public-accounts/2019/2019public-accountsvolume-i.pdf. Newfoundland and Labrador does the same for its main public-service plan, which covers employees in its colleges and hospitals.
Such treatment makes sense if the employers will, under reasonably foreseeable circumstances, avoid exposure beyond minimal changes to contribution rates. For recently established plans that have not undergone significant stresses affecting their contribution bases or their investment returns, it makes sense to ask for assurance about those assumptions. At the moment, there is no widely accepted threshold for determining when an employer’s funding risk is small enough to ignore, therefore, making DC accounting appropriate.
Another frequently cited justification for omitting the operations and financial positions of public-sector contingent plans from the employer’s financial statements is that the employer is not a plan sponsor, and is therefore not significantly exposed to the plan. While this is an important distinction for some purposes, a sponsor representing employers in a multi-employer plan will have no capacity to fund a shortfall: any funds required from the employer side will need to come from the employers themselves.
Multi-employer Arrangements: Employer Exposure Too Hard to Calculate?
Administrative convenience has also favoured DC treatment for multi-employer contingent plans. Translating the annual costs and cumulative obligations of a pension plan into the annual costs and cumulative obligations of each employer is not straightforward: each participating organization’s employees will have different demographic, earnings and other profiles. Accounting is a practical exercise, and decisions about what information to gather and report reflect judgments about whether the value of information is great enough to justify the cost of obtaining it.
The technical challenges of reflecting the operations and position of multi-employer plans in financial statements has led employers to treat these plans as though they were DC plans. PSAS sanctions this practice,1717 “When benefits are provided to employees through a multi-employer retirement benefit plan, each entity participating in the plan, other than the sponsoring government, should follow the standards for defined contribution plans (CPA 2017).” which is widespread.1818 Examples of employer explanations of their use of DC accounting are available in the financial statements of the Winnipeg Regional Health Authority, the University Health Network in Toronto and the City of Calgary. Defined contribution accounting is applied for multi-employer pension plans, whereby contributions are expensed on an accrual basis, as the Authority has insufficient information to apply defined benefit plan accounting.” (Winnipeg Regional Health Authority, Consolidated Financial Statements for the year ended March 31, 2019. See https://wrha.mb.ca/files/auditedfinancial-statements-1819.pdf.) “Defined contribution accounting is applied for the Healthcare of Ontario Pension Plan (“HOOPP”), a multi-employer pension plan, whereby contributions are expensed on an accrual basis, as UHN has insufficient information to apply defined benefit plan accounting.” (See https://www.uhn.ca/corporate/AboutUHN/Fiscal_ Accountability/Documents/AR_Financial_2018_2019.pdf.) “Due to the multi-employer nature of these plans [the LAPP and the SFPP], information is not available to determine the portion of the plans’ obligations and assets attributable to each employer. Therefore, The City appropriately accounts for both plans following the standards for defined contribution plans. The amount of expense recorded in the consolidated financial statements is equal to The City’s current service contributions to the plan as determined by APS for the year and no obligation is recorded in The City’s financial statements.” (https:// www.calgary.ca/cfod/finance/Documents/Plans-Budgets-and-Financial-Reports/Annual-Reports/Annual-Report-2019. pdf.) But potential problems with this practice are clear. If some or all of the employees of a publicsector employer participate in a pension plan that is not a DC plan, and the employer uses DC accounting to record only its contributions to that plan in its financial statements, what happens? The government that controls and/or has material financial exposure to the employer may also show nothing. In that case, people interested in the overall service capacity of the broader public sector will not find relevant information in either set of financial statements. The absence of any measure of differences between the value of accruing benefits and contributions will distort measurements of labour costs and annual surpluses or deficits. Similarly, the absence of any measure of the plan’s ability to meet its obligations may understate the taxpayer’s formal or practical exposure and mislead citizens about the capacity of their public-sector entities to deliver future services.
Alternatively, the government can reflect the difference between the benefits accruing in the plan and the plan’s capacity to cover those benefits in its own statement of operations. The plan’s accumulated surplus or deficit then appears in its own statement of financial position. This approach makes some relevant information available, but creates an appearance of control and responsibility that is problematic.
In or Out? Defining the Reporting Entity
Degrees of control, exposure and responsibility are central to the next key challenge: defining the reporting entity. Public-sector employers come in many forms, and deciding what to include in their financial statements or the financial statements of the relevant government involves many considerations. Take control, a foundational concept in accounting. In its Draft Revised Conceptual Framework for the Canadian Public Sector, the PSAB describes it this way:
Control is the basis used for associating economic resources, separate organizations and other arrangements with an entity that is reporting. Control is the power to govern the financial and operating policies related to these resources, entities and arrangements, with expected benefits or risk of loss accruing to the reporting entity (PSAB 2018a, p23).
Although legal ownership and control tend to run together, they are not identical. As the PSAB’s Draft Framework elaborates, one organization can direct the use of resources owned by another. Various legal and institutional constraints may affect control. Because governments have unique coercive power, the draft emphasizes that ability to raise economic resources in the future is not the same as the ability to control them in the present. It also emphasizes that influence over and regulation of activity is not the same as control.1919 For example, the draft notes that a government may have the ability to appropriate a private sector organization, but that this potential does not mean that the government controls it (PSAB 2018).
Financial exposure and control also tend to run together, but are distinct concepts. Control as defined in the Draft Framework would typically involve financial exposure, but as a practical matter, financial exposure can exist without it. Political pressure can result in governments backstopping many entities they do not formally control, as the COVID-19 crisis has freshly demonstrated. And governments may respond to practical financial exposure, or the appearance of it, by attempting to exert control in areas they previously left alone.
The absence of bright lines determining whether many employers and other organizations belong in a given reporting entity means that circumstances, including historical precedents, help explain what is in and what is out. Before considering the broader public-sector entities whose pension plans are the core focus of this Commentary, it helps to say a few things about the spectrum of entities that definitely belong, definitely do not belong and might belong in a government reporting entity.
At the must-include end of the spectrum would be activity that is a core government service, such as national defence. Military spending clearly belongs in the federal government’s financial statements. Some of that spending is deferred compensation, notably pensions for Canadian Forces personnel. Since the federal government is the sole sponsor of the Canadian Forces Pension Plan, a definedbenefit plan, it is uniquely responsible for the payment of those pensions. Federal taxpayers will benefit over time if the plan’s assets exceed its obligations, and they will suffer if the plan’s obligations exceed its assets. Therefore, Ottawa’s financial statements should include the operations and financial position of that plan – and they do.2020 The federal government uses an unreasonably high discount rate in valuing the future payments from this and other plans. As Robson and Laurin (2018) document, the federal government’s guarantee of these payments makes Government of Canada bond yields a better discount rate to use in such valuations. Using bond yields raises the estimate of the liability in the federal government’s plans by about one-third, or $100 billion.
Crown corporations are close to this end of the spectrum. Being their sole shareholders, governments have far more control over Crown corporations than over corporations in which they are minority shareholders, hold indirect stakes through other entities or have no ownership interest at all. The decision to carry out an activity through a Crown corporation rather than a government department reflects intention for a more arm’slength relationship. Indeed, Crown corporations have their own boards of directors and reporting structures. Yet governments typically consolidate their Crown corporations in their financial statements and, when they do, they also consolidate any pension plans those corporations sponsor.2121 Governments do not consolidate some Crown corporations and other government business enterprises that raise substantial shares of their revenues from commercial activity line by line, but show them as equity investments. The value of the government’s holdings, which would reflect any net worth related to pensions reported by the corporation, would register in the bottom lines of the government’s statements of operations and financial position.
Private corporations are at the opposite end of the spectrum. Governments do not direct the affairs of companies in which they hold few or no shares. The directors and managers of a private company have fiduciary duties to shareholders, whose interests may conflict with those of governments. Although governments regulate many business activities, and could potentially regulate many more, it makes no sense for governments to include the revenues and expenses of banks, say, or manufacturing, telecommunications or retailing businesses with their own, nor to include their assets and liabilities.
In between are entities in the broader public sector. Organizations such as school boards, universities and colleges, hospitals and other healthcare providers typically receive most of their revenue from governments. But they are separately incorporated organizations with their own boards of directors or trustees. Many have considerable autonomy, including in raising revenue from nongovernment sources, and in authorizing expenses.
When it comes to presenting a full, informative picture of the public sector’s capacity in a given province to deliver services, choosing what to include and exclude involves judgments that differ from one province to the next and may change over time.
Review of Current Practices and Tensions
For a closer look at current practices in the broader Canadian public sector, this section looks at the organizations that provincial governments may include in their financial statements. It first looks at the employers – organizations whose primary purpose is providing services such as healthcare or education. It then turns to the plans – the organizations whose primary purpose is providing pensions.
Consolidation, or Not, of Employers
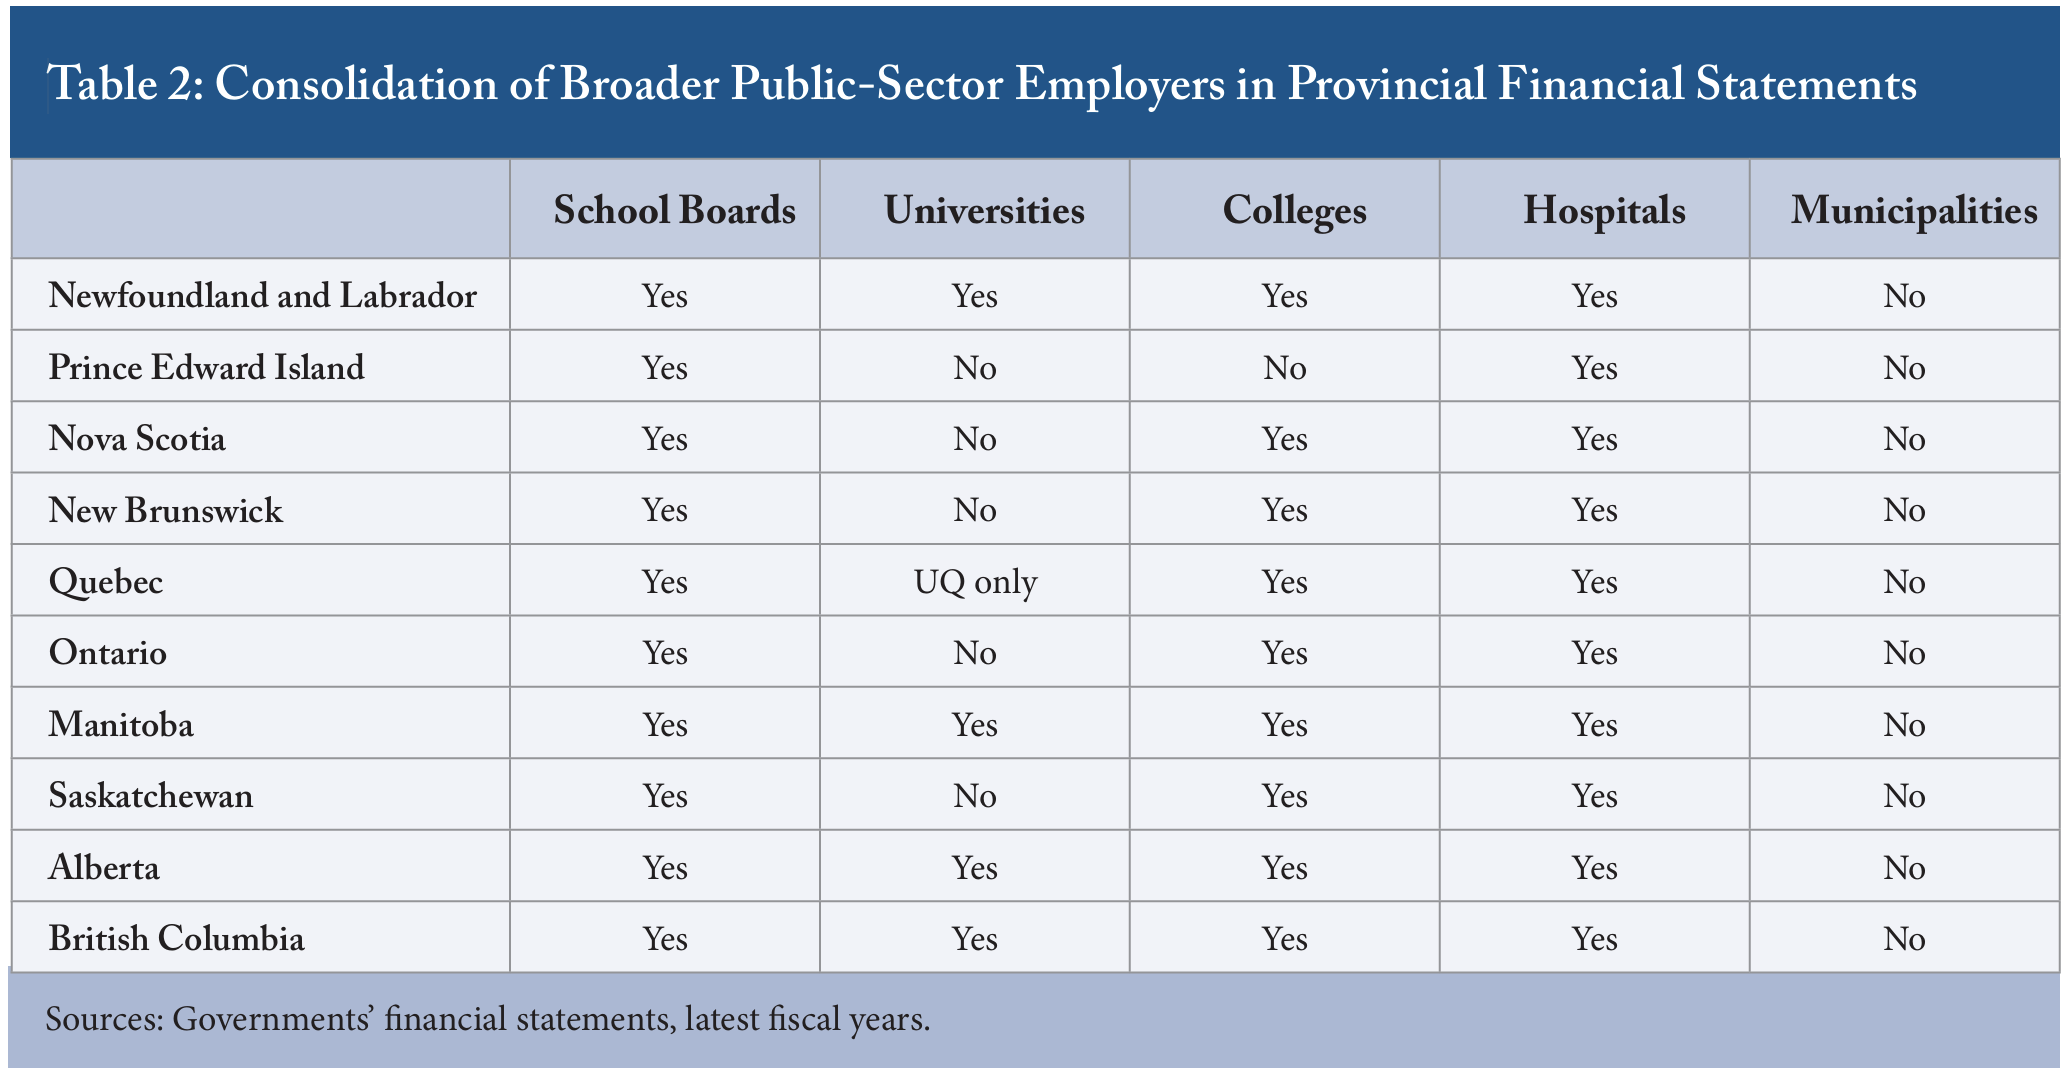
School boards are separately incorporated entities with their own boards of trustees. But centralization of funding and much else in the delivery of elementary and secondary education has led all provinces to consolidate school boards in their financial statements.
Hospitals are separately incorporated entities with their own boards of trustees. But since hospital care became largely publicly funded in all provinces, they have increasingly been thought of as part of the public sector. All provinces now consolidate publicly funded hospitals in their financial statements, either directly or through their health authorities.2222 The consolidation of hospitals in provincial financial statements was accompanied, and not by coincidence, by expressions of desire for more control by provincial governments and concerns on the part of hospital trustees about their loss of autonomy. See Quigley and Scott (2004) for comments from the perspective of Ontario hospitals. Most of them do not consolidate other healthcare institutions, such as longterm care homes, but some do. New Brunswick consolidated nursing homes in its 2019 statements, and COVID-19 may lead to other changes in provincial control and consolidation of long-term care organizations.
Postsecondary education is a mixed picture. Universities are incorporated, with their own boards of trustees. Most receive most of their revenue from governments, but universities usually have considerable autonomy in raising other revenues. Their treatment across the country varies. Newfoundland and Labrador consolidates its universities. The Maritime provinces do not. Quebec consolidates the Université du Québec system, but not other universities. Ontario and Saskatchewan do not consolidate universities. Manitoba, Alberta and BC do.
As for colleges, all provinces except PEI consolidate them, even though colleges vary in their dependence on government funding, with Quebec’s Collèges d’enseignement général et professionnel (CEGEPs) being at the more dependent/controlled end of the spectrum, and colleges elsewhere being more like universities in their degree of funding autonomy and independence.
Municipalities are, in the language of constitutional lawyers, creatures of provinces. Yet they are separately incorporated entities with councils elected by their citizens and have considerable legislative, revenue-raising and spending powers. No province consolidates its municipalities in its financial statements.
Table 2 shows the major categories of broader public-sector employers consolidated, or not, in provincial financial statements.
Inclusion, or Not, of Pension Plans
When employers that report the operations and financial position of their pension plans in their financial statements are consolidated with their province, the province’s financial statements will reflect those plans. But things are not always that straightforward. Employees of one employer or category of employer may participate in different multi-employer plans, and multi-employer plans may cover employees in different sectors.
Table 3 shows the same categories of employer as in Table 2 along with some of the plans that cover them.
Among the important examples of employees in more than one sector covered by a single pension plan is Quebec’s Régime de retraite des employés du gouvernement et des organismes publics (RREGOP), which covers employees in the provincial public service, education, health and in social services. Alberta’s Local Authorities Pension Plan is another: in addition to covering Alberta’s municipal employees, it covers employees of the Alberta Health Authority, Alberta’s colleges and non-teaching employees of Alberta school boards.

Among the examples of employees of one type of employer covered by different plans are the different plans that cover teaching and non-teaching staff in the school boards of several provinces, including Alberta, Ontario, Saskatchewan and BC.2323 The focus of this discussion is pension plans that cover employers in different sectors. A less salient example is employers in the same sector covered by different plans, as for example in Manitoba and Saskatchewan, where many larger municipalities have single-employer plans and smaller ones participate in a multi-employer plan (Baldwin 2015). Healthcare is another sector in which different plans often provide coverage to different worker categories – healthcare providers, for example, may participate in different plans than the support workers in the same institution.
Meanwhile, when it comes to reporting pensionrelated costs and exposure, provincial sponsorship of a plan is a decisive factor. Clearly, when a province is a sponsor, it must include them. But provinces are rarely sponsors of multi-employer plans.
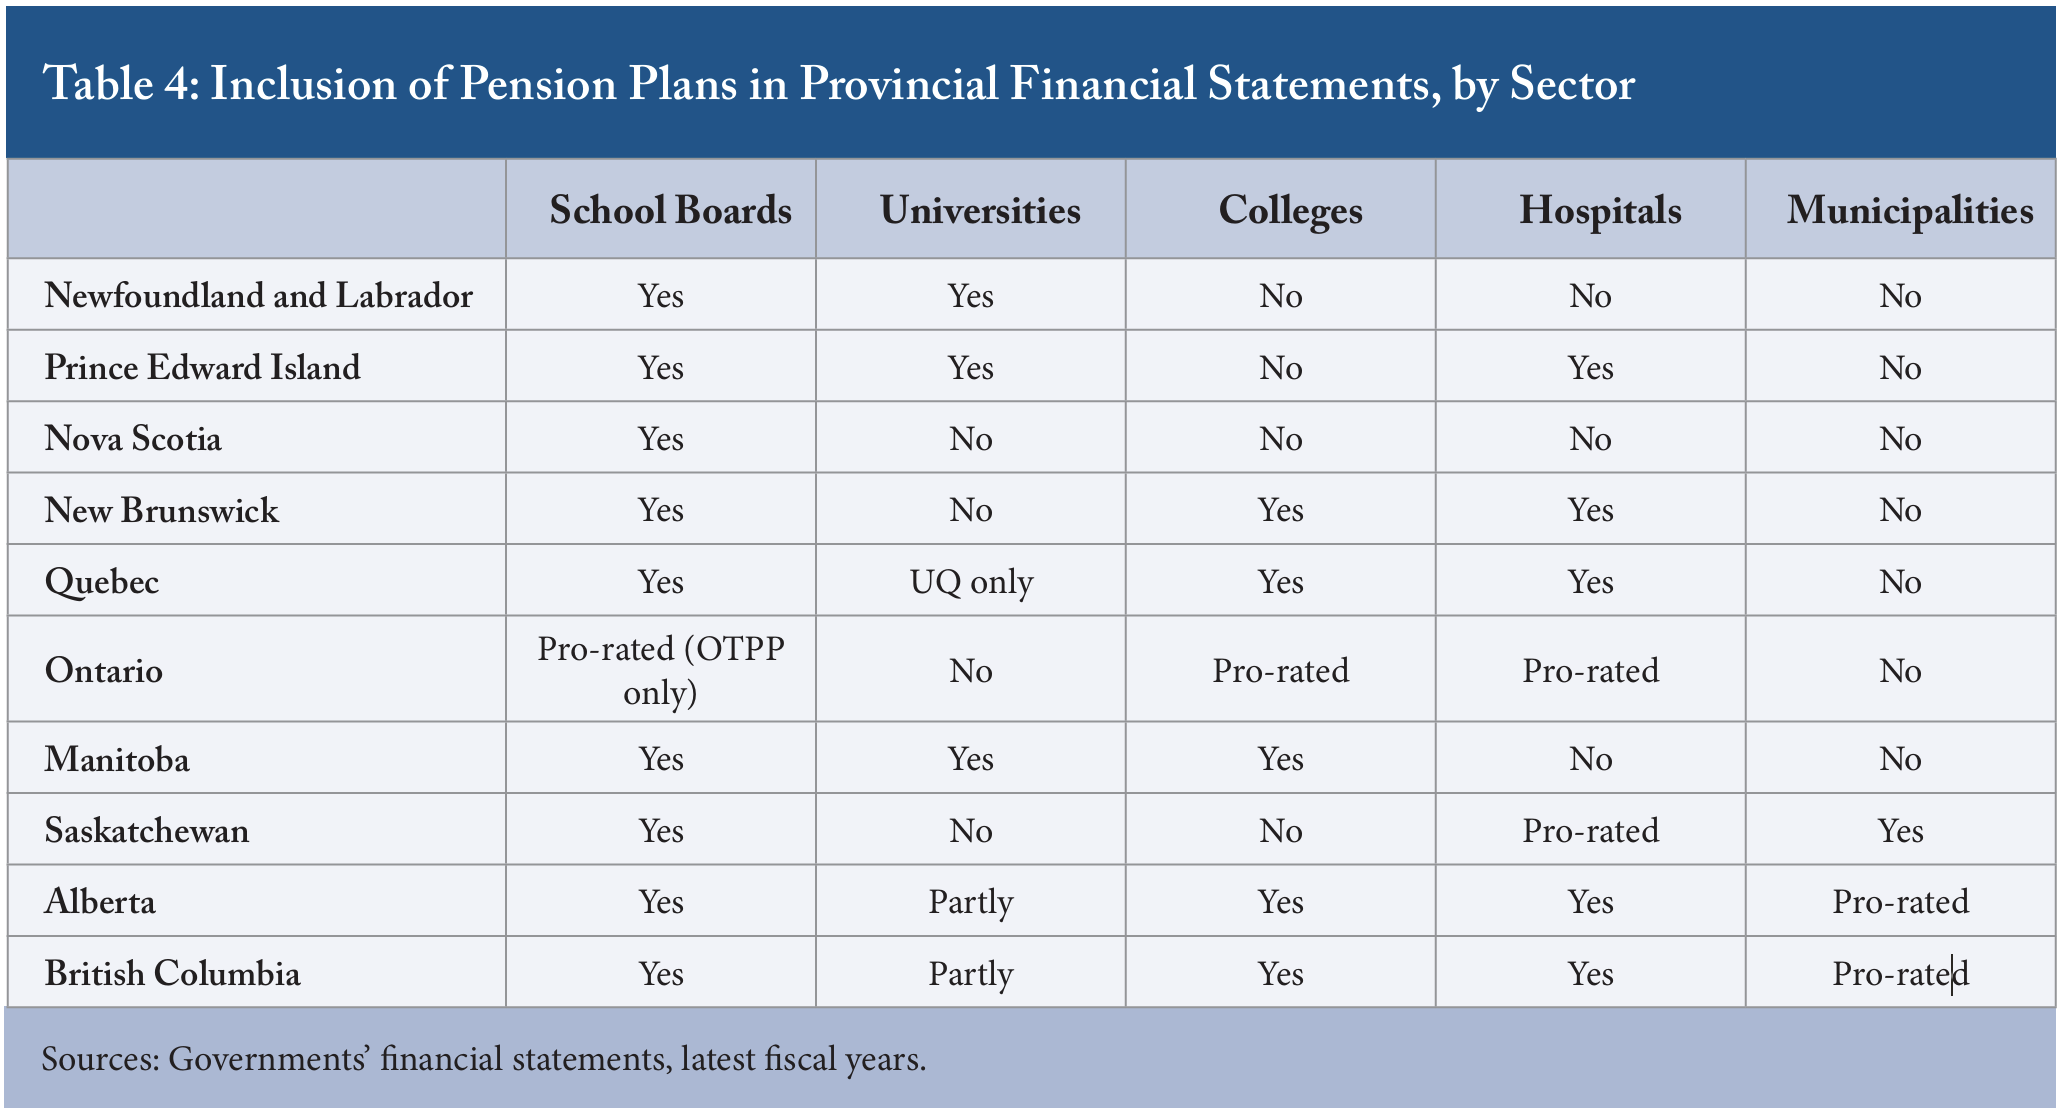
Using the same breakdown by type of institution that appeared in Tables 2 and 3, Table 4 summarizes, by province, the inclusion, or not, of the pensions covering the relevant employees in their financial statements. In cases where the employers are consolidated, but those organizations use DC accounting, the relevant cell shows a “No,” since the consolidation will reflect only the annual contributions of those employers.
Nova Scotia provides some notable examples of DC accounting. The employers it consolidates use DC accounting for their contingent plans, and the province itself also uses DC accounting for contingent plans of provincial employees.2424 Nova Scotia includes other pension plans in its financial statements, including its Teachers’ Pension Plan, for which it shows one-half of annual expenses and one-half of cumulative obligations. Another example of DC accounting at both the employer and provincial levels is Manitoba’s healthcare sector. In Ontario, the employers of participants in OMERS, which up to now has been a pure DB plan, use defined-contribution accounting, while the province’s financial statements reflect neither the operations nor financial position of that plan.
In other cases, employers and provinces who are not sole sponsors of pension plans use asymmetrical accounting. The logic behind the asymmetry is they are exposed to deficits, but do not have legal title to surpluses. For this reason, excesses of obligations over assets appear in the financial statements. Excesses of assets over obligations, on the other hand, do not. Employers or provinces include a “valuation allowance” equal to the excess, reflecting their lack of unilateral control, reducing the surplus’s impact on their statements of financial position to zero.2525 The valuation allowance may appear in the financial statements of the province itself, or it may appear in the financial statements of the relevant entity, as for example in the case of the Saskatchewan Health Authority. (See https://www. saskhealthauthority.ca/about/Documents/2018-19-SHA-Annual-Report.pdf.)
It is not unusual for provinces with contingent plans in their broader public sectors to use this asymmetrical reporting treatment when they include plans in respect of which the employers use DC accounting. Ontario does it for the Ontario Teachers Pension Plan (OTPP) and the Ontario Public Service Employees Union Pension Plan (OPSEUPP).2626 Like some other contingent plans, the OPSEUPP is often referred to as a DB plan. Since inflation adjustment of benefits is at the discretion of its trustees, who must take account of the plan’s funded status deciding whether to adjust or not, it is a contingent plan. These are jointly sponsored plans: the province cannot unilaterally access any surpluses in them, and its financial statements therefore offset any surpluses with a valuation allowance.2727 For several years, Ontario did not include a valuation allowance to offset surpluses recorded for the OTPP and the OPSEUPP. The provincial auditor general qualified her opinion on its financial statements as a result. The province now uses a valuation allowance, and the provincial auditor general has given an unqualified opinion.
Many provinces also use a valuation allowance to include pension plans in their financial statements, even when they are not plan sponsors. Ontario does it for the Healthcare of Ontario Pension Plan (HOOPP) and the Colleges of Applied Arts and Technology Pension Plan (CAATPP). New Brunswick, Manitoba, Saskatchewan, Alberta and BC do it for multi-employer plans they do not sponsor. The justification is that the provinces have exposure through their funding of the employers. When the plans have a deficit, the provinces record a liability related to their estimated exposure. When the plans have surpluses, valuation allowances reduce the impact on the provincial bottom line to zero.
In recent years, a phenomenon not captured by the above discussion of sectors and coverage has become important: plans covering employers in the public sector and broader public sector that also cover other employers. HOOPP, for example, originated in a private agreement between the Ontario Hospital Association and four healthcare sector unions. It covers both employees in hospitals, which are generally considered as public-sector organizations and are consolidated in provincial financial statements, and long-term care homes, which are not generally considered as publicsector organizations and are not consolidated. The CAATPP has a plan called “DB-Plus” that is a contingent arrangement covering employees in a number of private- and not-for-profit organizations outside the plan’s base in Ontario community colleges. BC’s Municipal Pension Plan (MPP) covers substantial numbers of employees for which the BC government judges that it has no exposure. The same is true for Saskatchewan’s Health Employees’ Pension Plan (SHEPP).
The province of Ontario reflects HOOPP and CAATPP in its statement of financial position – liabilities if they exist, otherwise surpluses written down to zero by a valuation allowance, pro-rating the amounts according to the share of contributions by broader public-sector employers to the plans, which is currently about half in each. BC uses the same asymmetrical approach to include roughly 70 percent of the MPP annual costs in its expenses and the same proportion of the plan’s assets and accrued benefit obligation in its statement of financial position. Saskatchewan does likewise in respect of roughly 90 percent of the SHEPP’s annual costs and net accrued obligation.
Potential Gaps and Tensions
One point arising in the discussion to this point is that differences between the employer and province in the accounting for pensions in the broader public sector can create gaps.
Pension-Related Costs and Obligations that do not Appear Anywhere
A key gap relates to the use of DC accounting – showing only contributions to the plan as expenses – in contingent plans. Contingent plans by their nature expose employers and sponsors to developments – good or bad – that affect the cost of delivering benefits. Treating them like DC plans means that the financial statements of the employer, and of the government if it stands behind the employers, may omit valuable information.
Employers who sponsor contingent plans but show no expenses beyond current contributions in their statements of operations, and nothing related to pensions in their statements of financial position, may mislead readers of their financial statements about their capacity to deliver future services. Likewise, provinces that have financial exposure to contingent plans and do not reflect it in their financial statements may mislead readers of those statements about their capacity to deliver future services. Risks borne by the employer – and potentially, through the employer, by the taxpayer – are nowhere in sight.
One example mentioned earlier is Nova Scotia, where the financial statements of neither the province nor the broader public-sector employers whose employees participate in its contingent plans show deviations between the cost of accruing pensions and annual contributions, nor the cumulative surpluses or deficits arising from those deviations. Another example above is Ontario, where the financial statements of municipalities and other entities that employ participants in OMERS use DC accounting, and the province shows no exposure to the plan. In the absence of clear rules and protections that limit the exposure of employers and the province to material changes in contribution rates, employer and provincial financial statements using DC accounting may give an inaccurate picture of the public sector’s service capacity.
Pension-Related Costs and Obligations that Appear in the Wrong Place
When employers bearing significant pensionrelated financial risk use DC accounting, it makes sense for a province exposed to the risks DC accounting hides to report it themselves. Otherwise, the costs and obligations will not appear anywhere. There are, however, several reasons why disclosure at the provincial government level – even in notes to the financial statements rather than in the statements themselves – is less satisfactory than reporting by the employer would be.
One problem worth at least a passing mention is the use of a valuation allowance to offset any pension-related surplus that would otherwise appear in the financial statements. Notwithstanding the legal and practical justifications, the asymmetry of including deficits but not surpluses means that financially healthy plans and the presumably greater service capacity of the employer or government will not show in their financial statements. It almost certainly makes the disclosure harder to understand for the non-expert user of financial statements.
A respectable argument exists, moreover, that this asymmetry might affect future behaviour, which would be particularly problematic at the provincial level. For example, a province may be less interested in promoting prudent practices among the employers and pension plans in its broader public sector if surpluses do not improve its own reported financial position. Should less prudent practices produce deficits, on the other hand, the plans, employers and participants might be more inclined to expect a provincial bailout, since the province is already showing the deficits on its books. While reporting exposures in notes to a province’s financial statements rather than in the statements themselves might mute the message about a potential bailout, the message would still be there.
In view of the difficulties and controversies over the appropriate discount rate to use in valuing future payments, another potential discrepancy merits mentioning. Even if the principles determining the inclusion of pension-related costs and obligations in a province’s financial statements are straightforward – an employer that has pension-related exposure is part of the government and, therefore, its pension-related exposure should appear in the provincial financial statements – the province might disagree with the assumptions used by the pension plan and/or the employers. A relevant example is a province using a different discount rate from that used by the plan or the employer. Indeed, Ontario uses a higher discount rate when reporting its exposure to OTPP, HOOPP and CAATPP than the plans themselves use.
Few people are aware that provinces use higher discount rates in reporting the pension obligations of the employers and/or plans in their financial statements than the employers and plans themselves, or that this practice flatters provincial financial statements and works against the goal of consolidation.2828 For a province to report its exposure to pension obligations even when it is not a plan sponsor or formally obliged to backstop a plan might be justified on grounds of prudence – alerting citizens and taxpayers to a risk. However, a truly prudent approach would use the same discount rate that the plans use, or a discount rate reflecting the province’s cost of borrowing and the value of the backstop. Using a higher discount rate, which shrinks the recorded size of the obligation, does not look like prudence. Such practices should not continue. As long as they do, they merit a warning in the notes to the provincial financial statements.
Perhaps most important of all is the ambiguity that reflecting pension costs and obligations in the province’s financial statements can create about who bears the risks in a plan. In his 2012 report on Ontario’s finances (Commission 2012), economist Don Drummond noted the confusion about who bears ultimate responsibility for the deficits that then existed in Ontario’s public-sector pension plans.2929 Recommendation 19-5: “Clarify who bears the ultimate financial responsibility for funding deficits of the public-sector pension plans as the Commission encountered considerable confusion on this issue” (Commission 2012, p. 433). That same criticism could be made, not just of Ontario, today. DC accounting implies that the employer bears no risk – that all the risk is on the participants. Contingent plan documents are clear, to the participants that read them, that participants bear some risk. But if the province is showing the plans – or at least their annual and cumulated deficits – on its own books, the implication is clear that the province and, through the province, taxpayers are bearing the employer-side risk.
That implication may affect behaviour. If the sponsors, participants and managers of a pension plan anticipate a backstop from taxpayers – whether a direct injection of funds into the plan or indirect support through transfer payments to the employers – they may be less attentive to the plan’s management and performance, which could make a situation where the backstop might appear necessary more likely. For similar reasons, showing the exposure may increase the temptation for a province to assert control over the plan.
The Heterogeneity of Pension Plans in the Broader Public Sector
The fact that some pension plans cover employees of organizations governments control as well as employees of organizations governments do not control is not merely a challenge for the tidyminded. It may influence the expectations of participants and others about who is responsible for the good governance and financial sustainability of the plans.
Contingent pension plans are an important innovation, balancing participants’ desire for benefit security against the flexibility needed to adapt to surprises and mistakes. Participation in plans with substantial public-sector employment may be more attractive to people who think that governments will force taxpayers to cover shortfalls, with the result that current and potential participants may scrutinize the sponsors, trustees and management of those plans less carefully than they would without that real or implied government backstop. Employers may opt for such plans because of the advantages of defined-contribution accounting, thinking that a government will bail out the plan if the contributions are insufficient to pay the promised benefits.
Accounting that reflects the mix of risks and obligations on employers and employees of government and non-government organizations will not, on its own, solve these problems, but without it, confusion is inevitable and bad behaviour more likely.
Next Steps
Now is the time for a re-examination of rules and practices for reporting pension costs and risks in the broader public sector. The PSAB is reviewing the reporting of deferred compensation, with contingent pension plans being a key focus. Some pension plans in the broader public sector are offering coverage to new entities, including entities that are clearly not under government control. Employees and employers considering that option should not expect government backing for their pension promises and should not receive it if they do expect it.
Meanwhile, new contingent plans are starting up, such as Ontario’s University Pension Plan. These new plans and their participating employers must report their costs and obligations appropriately. It would be a problem, for example, if the lure of DC accounting led employers to participate in these plans in the expectation that they need not report any ongoing exposure. It is important that governments present information that accurately reflects any changes in their own obligations created by these plans. All this needs considering in the context of accelerating retirements and pension obligations that are transmuting, changing from aggressively discounted liabilities – or even unreported ones – into actual cash requirements.
Employer Reporting: When is DC Accounting Appropriate?
A question that needs a clear answer is: when is DC accounting for pension obligations appropriate? When is the exposure of the employer to positive or negative developments affecting a contingent plan’s ability to pay promised benefits small enough to ignore?
Target-benefit pension plans that can adjust benefits, including accrued benefits, enough to keep contributions within a narrow band – say 1 percent either side of the current rate – would seem reasonable candidates for that treatment.3030 It is common for pension plans, regulators and standard setters to distinguish between accrued benefits that reference variables other than inflation and accrued benefits related to inflation. This is because conditional inflation indexation has long been a feature of pension plans, with other benefits – “base benefits” – being seen as more fundamental and unalterable. From an economic point of view, this distinction makes no sense: a dollar of benefit will have the same real value to the recipient and the same cost to the plan regardless of whether any adjustment reflects a change in the “base” amount or a change in the inflation adjustment. Making the definition of a target-benefit plan contingent on that distinction would likewise make no sense. But the burden of proof for applying DC accounting ought to rest on those seeking to apply it.
A key selling point of the contingent pension plan model is benefit security beyond what a DC plan offers. If an employer is bearing material risk to provide that security, the employer’s financial statements should show those costs as they accrue, and the cumulative costs accrued over time.
With respect to record-keeping and related administrative burdens as justifications for DC accounting, the burden of proof should be on those defending the practice.3131 The responses to PSAB’s invitation to comment on this issue (PSAB 2019) reveal a range of opinions. Many comments highlight the administrative complexity of requiring employers to move away from DC accounting. Others point out that DC accounting in contingent plans deprives users of valuable information. Contingent plans in Canada’s broader public sector cover millions of employees and have assets and liabilities in the hundreds of billions of dollars. Their potential implications for employers who bear material risk is correspondingly large. Record-keeping limitations may make it impossible to generate precise estimates of obligations for each employer in a multi-employer plan that has reported on a pooled basis for years, but pro-rata calculations based on aggregate estimates are much better than nothing. It is better to be roughly right than precisely wrong in financial reporting. Employers who are incurring and/or already bear material risk and show nothing on their statements of operations and financial position are being precise – zero is a precise number – and wrong.
As noted above, Ontario, Saskatchewan and BC report their exposure to multi-employer plans – HOOPP and CAATPP in Ontario, the SHEPP in Saskatchewan and the MPP in BC – on the basis of their contributions to the plans. Whatever the merits of their doing so in respect of these particular plans, any employer can do likewise.
Going forward, modern payroll services that track employees’ ages, salaries and other characteristics can help employers generate better estimates of the benefits accruing to their workforces. The best entities to report pensionrelated risks are the employers themselves: school boards, post-secondary and healthcare institutions, and municipalities that provide labour-intensive front-line services, all of whose fiscal health and service capacity are matters of vital interest. Advances in information technology are lowering the costs of gathering and processing relevant financial information, while the increasing materiality of the obligations and improving standards of disclosure are enhancing the potential benefits.
As noted earlier, a relevant development in this front is the recent rule from Canada’s Actuarial Standards Board that identifies the ability to reduce accrued benefits while a plan is ongoing as a defining feature of a target-benefit arrangement. If that capability is sufficient to ensure that employer contributions will not vary beyond a de minimis threshold – say one percentage point – and there is no obligation to fund a wind-up deficit, DC accounting might be appropriate. Clarity from PSAB on the governance principles and/or specific criteria that would justify a label such as “TargetBenefit Plan” and qualify such plans for DC accounting would be helpful.
If guidance from PSAB is not forthcoming, provinces and employers should take a critical look at current practices. At the very least, employers should add notes to their financial statements describing the relevant plan or plans, whether they had surpluses or deficits as of their most recent valuation and describing the assumptions behind those valuations sufficiently that an informed reader can understand the basis for the judgment. At least some broader public-sector contingent plans in Canada likely expose employers and therefore taxpayers to more risk than is safe to ignore.
Provincial Reporting of Pension Exposure: Whether and What to Show
Decisions about which organizations and activities should or should not appear in governments’ financial statements will depend on many criteria, some beyond the scope of this Commentary. With respect to pension obligations, however, the potential impacts of such decisions merit repeating.
Including an organization’s operations and financial position in its financial statements creates the appearance of and, in political terms, likely also the reality of responsibility for that organization’s operations and financial position. At budget time, the organization’s revenues and expenses affect the government’s revenues and expenses. At yearend, its conformity, or lack thereof, with budgeted forecasts affect the government’s success, or failure, in achieving its fiscal plan. Some or all of its assets and liabilities blend into the government’s assets and liabilities – material to judgments about the government’s fiscal position and capacity to deliver services. Inclusion not only reflects control, it reinforces it.
However, reflecting exposure to a pension plan can also create moral hazard. It may undermine discipline in the plan and/or encourage interference, increasing the chances that an implied backstop becomes an actual one.
When it comes to reflecting the operations and financial position of pension plans in governments’ financial statements, the decision to consolidate (or not) employers such as school boards, universities, colleges and hospitals will determine whether exposure to pension plans in which those employers participate will appear in provincial financial reporting. If the employers use DC accounting, provincial financial statements will show nothing in respect of those pensions. If the employers realistically report their own exposure to pension obligations, so too will provincial financial statements. Therefore, it matters very much for accuracy of provincial financial reporting that consolidated employers accurately report their exposure to pension risks and obligations.
When employers use DC accounting for plans that expose them to risks too material to ignore, provinces face the separate decision of whether to reflect their own exposure and potential pressure to increase transfers to the employers. Doing so is a fraught approach, likely to tempt governments to interfere with plans that affect their bottom lines and fostering less responsible behaviour on the part of plan sponsors, participants and managers. For provinces that currently show such exposure to announce that they intend to stop the practice might have a salutary effect – alerting managers, employers and employees in the relevant plans that a backstop they might have been assuming was there is, in fact, not. It might also prompt important conversations about potential changes in plan governance and provisions that will ensure that the plan can survive without a backstop.
Because pension accounting is contentious, a further drawback of recognition other than through consolidation merits attention. Provinces, no less than pension plans themselves, like to present a positive representation of the bottom line. In reporting the financial condition of pension plans, they, too, feel short-term pressures to adopt assumptions that make current costs look low and accrued obligations easy to discharge – which is why they sometimes use higher discount rates when reporting pension obligations than sponsoring employers and/or plans themselves use. The more employers that provide pensions are consolidated in government financial statements, and the more governments report exposure to pensions that are not reported by consolidated employers, the more helpful the PSAB’s advice about discount rates will be.
These considerations reinforce the argument for employers themselves in the broader public sector to issue financial statements that show their material pension-related exposure. When they do, pension exposures of employers that are consolidated with the province will automatically appear in the province’s financial statements. Pension exposures of other employers should appear in the province’s financial statements only when the province has unambiguous responsibility as the plan sponsor.
Conclusion
Although the financial statements of Canadian governments and public-sector entities are relatively good, they could be better. Pension-related costs and future obligations are a key area for improvement. The amounts at stake, and their potential implications for governments’ service capacity, are large. Reflecting potential future payments in current financial statements is challenging, especially with the spread and refinement of contingent pension arrangements that limit, but do not eliminate, the exposure of employers to unknowable contingencies. A further complication in Canada’s modern mixed economy is the overlap between different pension plans and different sectors of the economy, some of which are clearly in the public sector and others which are not. Deciding what to count and how is hard, but necessary.
Among the key issues new rules could helpfully clarify is what kinds of pension plans lower employer-side risk to the point where it is safe to ignore. Meanwhile, since DC accounting is widespread, and access to it is a selling point for employers thinking about changing their pension arrangements, the PSAB should define the type of target-benefit arrangement that merits that treatment.
When pension plans do not make employerside risk small enough to ignore, their operations and financial positions should appear somewhere. The widespread practice of showing exposure at the provincial level – and potentially using notes to the financial statements to alert readers to contingent exposure – is better than not showing it at all. Still, the best place for them to appear is in the financial statements of the employers themselves. Several provinces already pro-rate their exposure to multiemployer plans in calculating their pension-related obligations, so the objection that employers do not have the information to calculate their own exposure does not seem convincing.
Although many considerations will affect any changes to PSAS when it comes to defining the reporting entity, this Commentary highlights arguments in favour of a narrower definition. With respect to broader public-sector entities generally, and pension plans in particular, broader definitions raise concerns about moral hazard. Consolidation may foster unhealthy attention on the part of governments to the behaviour and reporting of the employers and pension plans and may also foster imprudent behaviour on the part of the employers and plans themselves. Some of Canada’s pension plans in the broader public sector are world leaders in terms of transparency and prudent management. To the extent that revised PSAS both acknowledge and reinforce those characteristics, Canadians will better understand the service capacity of their governments and public-sector organizations, and be better able to demand change if that capacity is under threat.
References
Actuarial Standards Board. 2020. “Final Standards – Amendments to Section 3500 of the PracticeSpecific Standards for Pension Plans – Pension Commuted Values.” Ottawa: Canadian Institute of Actuaries. January. Available at: https://www.cia-ica.ca/docs/default-source/2020/220009e.pdf.
Baldwin, Bob. 2015. Municipal Employee Pension Plans in Canada: An Overview. Institute on Municipal Finance and Governance. University of Toronto.
Chartered Professional Accounts (CPA) Canada. 2017. CPA Canada Public Sector Accounting Handbook.
Commission on the Reform of Ontario’s Public Services. 2012. Public Services for Ontarians: A Path to Sustainability and Excellence. Toronto: Queen’s Printer for Ontario.
Finance Canada. 2019. “Economic and Fiscal Update.” December.
Gros, Barry, and Barbara Sanders. 2019. The Quest for Sustainability in Contingent Pension Plans. Commentary 553. Toronto: C.D. Howe Institute. September.
Public Sector Accounting Board. 2016. “Invitation to Comment – Employment Benefits: Deferral Provisions in Sections PS 3250 and PS 3255.” November.
________________. 2017a. “Invitation to Comment – Employment Benefits: Non-Traditional Pension Plans.” October.
________________. 2017b. “Invitation to Comment – Employment Benefits: Discount Rate Guidance in Section PS 3250.” November.
________________. 2018. A Revised Conceptual Framework for the Canadian Public Sector. May.
________________. 2019. “PSAB Invitation to Comment – Employment Benefits: Non-Traditional Pension Plans. Public Record and Reponse [sic] Booklet.” March.
Robson, William B.P. 2017. Rethinking Limits on Tax-Deferred Retirement Savings in Canada. Commentary 495. Toronto: C.D. Howe Institute. November.
Robson, William B.P., and Alexandre Laurin. 2018. Retiring Employees, Unretired Debt: The Surprising Hidden Cost of Federal Employee Pensions. Commentary 514. Toronto: C.D. Howe Institute. May.
Robson, William B.P., and Farah Omran. 2019a. Show and Tell: Rating the Fiscal Accountability of Canada’s Senior Governments, 2019. Commentary 545. Toronto: C.D. Howe Institute. June.
________________. 2019b. From A to F: Grading the Fiscal Transparency of Canada’s Cities, 2019. Commentary 560. Toronto: C.D. Howe Institute. December.
Steele, Jana R., Angela Mazerolle, and Mel Bartlett. 2014. Target-Benefit Plans in Canada – An Innovation Worth Expanding. Commentary 411. Toronto: C.D. Howe Institute. July.
Quigley, Maureen A., and Graham W.S. Scott. 2004. “Hospital Governance and Accountability in Ontario.” Ontario Hospital Association. April.
Usher, Alex. 2020. “Postcard from Alberta (1).” Higher Education Strategy Associates. 27 January. Available at http://higheredstrategy.com/postcard-fromalberta-1.
Additional Sources:
Annual reports (various) of school boards, universities, colleges, hospitals and pension plans mentioned.
Public Accounts (various), 2018-2019 fiscal year, of Canada’s senior governments.