


October 22, 2026 – The C.D. Howe Institute’s Monetary Policy Council (MPC) calls for the Bank of Canada to keep its target for the overnight rate, its benchmark policy interest rate, at 2.25 percent at its next announcement on October 28, increase it to 2.5 percent by next April, and to 2.75 percent by next October.
The MPC is chaired by Jeremy Kronick, the Institute’s President and CEO, and includes the chief economists of the six largest Canadian banks, alongside six leading academic economists and financial market experts.
Acting as a shadow Bank of Canada Governing Council, the MPC provides an independent assessment of the monetary stance needed to achieve the Bank’s 2-percent inflation target. Its formal recommendation for each interest rate announcement is the median vote of members in attendance. Members vote on the upcoming announcement, the subsequent announcement, and the announcements six months and one year ahead.
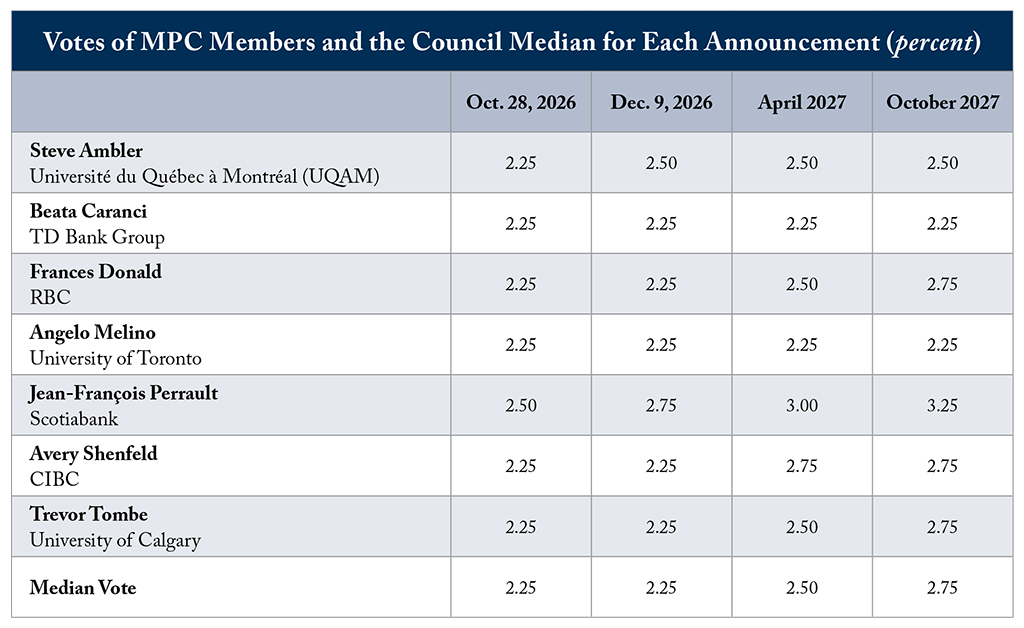
Six of the seven MPC members in attendance called for the Bank of Canada to hold the overnight rate target at 2.25 percent next week, with one member calling for a hike to 2.5 percent. For the Bank’s next meeting in December, five members voted to hold the overnight rate target at 2.25 percent, while one member voted to hike to 2.5 percent and another to 2.75 percent. Six months ahead, in April 2027, one member called for a 3 percent overnight rate target, one for 2.75 percent, three for 2.5 percent, and two for 2.25 percent. Looking out one year to October 2027, one member voted for a rate of 3.25 percent, three for 2.75 percent, one for 2.5 percent, and two for 2.25 percent (see table below).
A central theme of the discussion was the recent data releases and the shift in market expectations over the past week toward a rate hike at the Bank of Canada’s upcoming announcement. Members noted that headline inflation remained around 3 percent, driven by elevated energy prices. Core inflation, however, was still around 2 percent, indicating a continued lack of pass-through to other prices in the economy. Members saw little evidence of broader price pressures and, from that perspective, found it difficult to make the case for a hike, which most did not.
Some members, however, highlighted potential justifications for a rate hike. Consumer inflation expectations increased to levels last seen during the post-COVID inflation surge. Energy prices have remained elevated for some time, raising concerns that these costs will eventually pass through to other goods and services. The Business Outlook Survey indicated that firms expect to pass on more of their significant cost increases than what has already been passed through. The Industrial Product Price Index is elevated and is often an early warning of spread to the broader CPI. Members argued that credibility is playing a role here too, with elevated inflation coming not too long after the last surge.
Members who voted to hold made the case that the Bank still has time to wait to decide whether to hike, particularly with some major events on the horizon that will impact both the demand and supply side of the economy. How the US midterms in early November, the federal budget the same week, and the proposed 50 percent tariffs by the US on Canadian autos starting on January 1, 2027, play out could significantly influence inflation and the output gap.
Lastly, members mentioned that yields continue to be elevated further out the curve, tightening financial conditions without the need for a hike to the overnight rate. This reinforced a broader point: while the current inflationary environment shares similarities with the post-COVID inflation surge, important differences remain, including the starting point for interest rates across the yield curve.
Important Disclaimer: The views and opinions expressed by the participants are their own and do not necessarily reflect the views of the organizations with which they are affiliated, or those of the C.D. Howe Institute. Forecasters’ recommendations may differ from their predictions.
Seven of the 12 MPC members attended and voted in this meeting.
The MPC’s next vote will take place on December 3, 2026, prior to the Bank of Canada’s overnight rate announcement on December 9.
* * * * *
For more information, contact: Raquel Schneider, Communications Officer, 647-805-3918, rschneider@cdhowe.org.
Want more insights like this? Subscribe to our newsletter for the latest research and expert commentary.